
By Joseph T. Ellington Jr. – Licensed Residential Appraiser, Capital Valuations. Updated November 2026.
Why square-footage adjustments are not a fixed price per foot
When two houses differ in finished living area, an appraiser may adjust a comparable sale to reflect how buyers in that market react to the difference. The adjustment is not automatically the home’s sale price divided by its square footage. Fannie Mae says adjustments must reflect market reaction rather than a rule of thumb. A $20-per-square-foot shortcut can be wrong when evidence indicates a different adjustment. If you need the dimensions documented first, our measurement-only service addresses that separate question. This article explains the adjustment logic; our ANSI measurement guide addresses how area is measured.
Measurement comes before comparison
Confirm what the reported figure represents: finished above-grade area, below-grade finished space, an accessory dwelling unit, a garage, or another area. These categories can have different market appeal and reporting treatment. For applicable Fannie Mae assignments, see its improvements and above-/below-grade guidance. Tax records, listings, builder plans, and an appraiser’s measurement may differ in method or accuracy. Bring the underlying plans, permits, and prior measurement records so the appraiser can investigate the discrepancy.
How I support a square-footage adjustment
When I develop a size adjustment, I have several ways to analyze and check it. Matched-pairs analysis, sensitivity analysis, and depreciated cost can each help, depending on the property and the available evidence. The calculation matters, but so does understanding what caused the price difference.
I start with competitive sales and check their area data. Location, condition, construction quality, site, bathrooms, garages, sale terms, and market conditions can all affect the comparison. See our comparable-sales guide for how those properties are selected.
1. Matched-pairs analysis: isolate the size difference
With matched pairs, I compare sales that are similar enough to isolate a particular difference. For a living-area adjustment, material differences other than size must be accounted for before attributing the remaining price difference to square footage. Two sale prices and two area figures alone do not establish a reliable rate.
Here is a hypothetical example:
| Home | Living area | Sale price |
|---|---|---|
| A | 2,200 sq ft | $400,000 |
| B | 2,000 sq ft | $380,000 |
If the remaining $20,000 price difference is attributable to the additional 200 square feet, the indicated adjustment rate is:
($400,000 − $380,000) ÷ (2,200 − 2,000) = $100 per square foot.
That is a rate indicated by this hypothetical pair, not a standard rate for every home. If Home A also had a remodeled kitchen or a better location, I would need to address those differences. Additional pairs or another analytical method can help check the result. The Appraisal Foundation illustrates this same principle of isolating size differences in its paired-sales example.
2. Sensitivity analysis: test the adjustment across the sales
Another method is to test different adjustment rates in the software and examine what happens to the comparable sales’ adjusted prices. For example, I might test hypothetical rates of $50, $60, or other amounts per square foot while holding the other adjustments constant. This can help identify a rate or range that reduces the spread of the adjusted indications.
The rate that minimizes variance is a candidate to evaluate; a tight range alone does not establish that it correctly measures buyers’ reaction to size. The selection of sales, measurement accuracy, and support for the other adjustments still matter. A size adjustment can otherwise absorb differences actually caused by condition, location, or another feature.
Grouped-sales analysis and sensitivity analysis are distinct techniques. Grouped analysis compares sets of sales; sensitivity analysis examines how results change when an input changes. The Appraisal Institute includes both among the techniques used to support sales-comparison adjustments.
3. Depreciated cost: another way to support and check the adjustment
Depreciated cost can also provide useful evidence. Suppose relevant local construction costs were $150 per square foot and the supported depreciation estimate were 30%. The simplified calculation would be:
$150 × (1 − 0.30) = $105 per square foot.
These are hypothetical figures. The $105 result is a cost-based indication to assess alongside the market evidence, not an automatic living-area adjustment. The cost analysis should address the area or feature being compared; an average cost to build an entire house does not necessarily equal the cost of its additional living area. Land value is separate.
The depreciation percentage also needs support. In an economic age-life calculation, depreciation is estimated as effective age ÷ total economic life. A hypothetical effective age of 15 years and total economic life of 50 years would indicate 30%. Effective age reflects condition and utility, so it can differ from the number of years since construction. Physical deterioration and any relevant functional or external obsolescence must be considered.
The Appraisal Institute recognizes depreciated cost as a way to test the reasonableness of an adjustment. The California State Board of Equalization’s advanced appraisal handbook explains the effective-age calculation and its limitations. The final sales-comparison adjustment still needs to reflect the contribution of the size difference to value.
An illustration of the arithmetic, not an appraisal rate
Suppose a subject has 2,000 square feet of finished above-grade area and a comparable has 1,800. If independent local market analysis supported a hypothetical $60 per square foot difference for that range of homes, the area line for the comparable would be +$12,000 (200 × $60). This example only shows the direction and multiplication; $60 is invented for illustration and must never be reused as a Hampton Roads market rate.
| Item | Subject | Comparable | Example adjustment to comparable |
|---|---|---|---|
| Finished above-grade area | 2,000 sq ft | 1,800 sq ft | +200 × hypothetical $60 = +$12,000 |
| Other differences | To be analyzed | To be analyzed | Separate market-supported analysis |
For the reverse situation, where a comparable has more relevant living area, the direction of its adjustment generally reverses. A report should explain the support and how the appraiser weighs sales; see our value-reconciliation article.
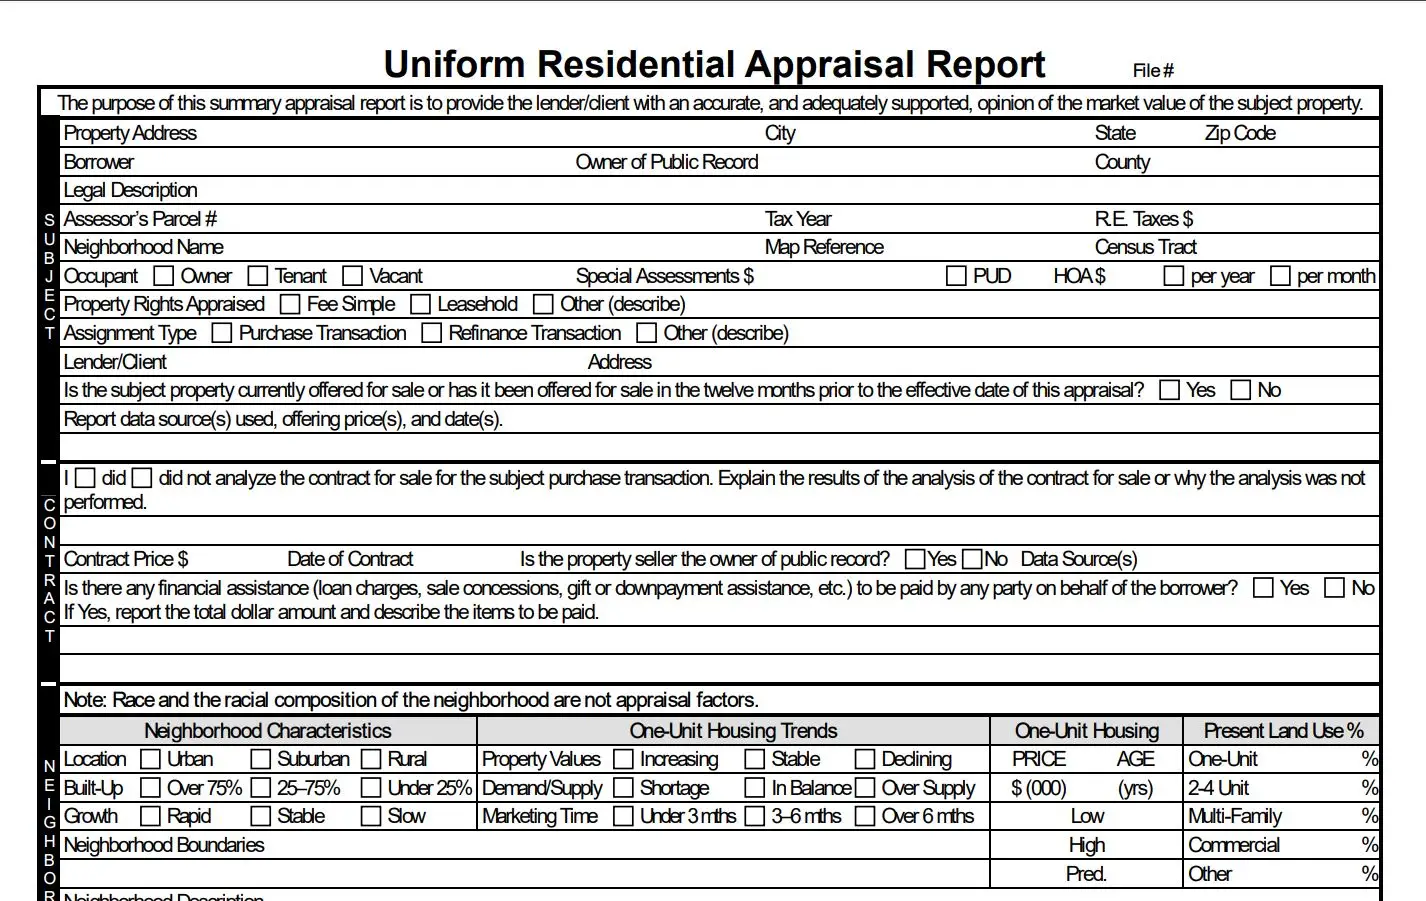
Questions to ask when the number seems wrong
- Are all comparable and subject area figures measured or described on a consistent basis?
- Does a finished basement or separate unit appear in the wrong category?
- Was an addition counted despite incomplete work or missing records?
- What sales and analysis support the specific area adjustment in this assignment?
- Could condition, room count, or location explain some apparent price difference instead?
If a lender appraisal has a factual error, contact the lender about its reconsideration-of-value process. Provide specific records and comparable evidence; the appraiser remains independent. For a private appraisal or measurement question in Hampton Roads, contact Capital Valuations with the property address and intended use.
