
The history of home appraisalFrom caves
to computers.
Home appraisal evolved through better property records, professional standards, new report formats and digital tools. I’ll walk through that history, then share what changed during my own career—and why an appraiser’s experience and judgment still matter.
Let’s travel through time ↓Fictional cavemen. Real milestones. Firsthand experience.
Pick a stop—or follow the whole story.
A fictional beginning
First, let’s get the caveman story straight
Our caveman guide, Rock, has a problem. The cave next door has a sunny entrance, a dry floor and a better view. Rock’s cave has a puddle. He insists they must be worth the same because they are both caves.
This is a made-up scene, of course. I’m not claiming that prehistoric people ordered home appraisals or hired licensed cavemen. The characters are here to help tell the story. The records and dates that follow are real.
The question behind Rock’s complaint is still recognizable: what makes one property different from another, and how much do those differences matter? That is a much better place to begin than assuming every similar-looking home has the same value.

ca. 2350–2150 BCE → 1086
Property records are older than paper files
People were recording house transactions thousands of years before anyone opened a laptop. The Metropolitan Museum of Art holds a clay tablet documenting a house-sale contract from approximately 2350–2150 BCE.1
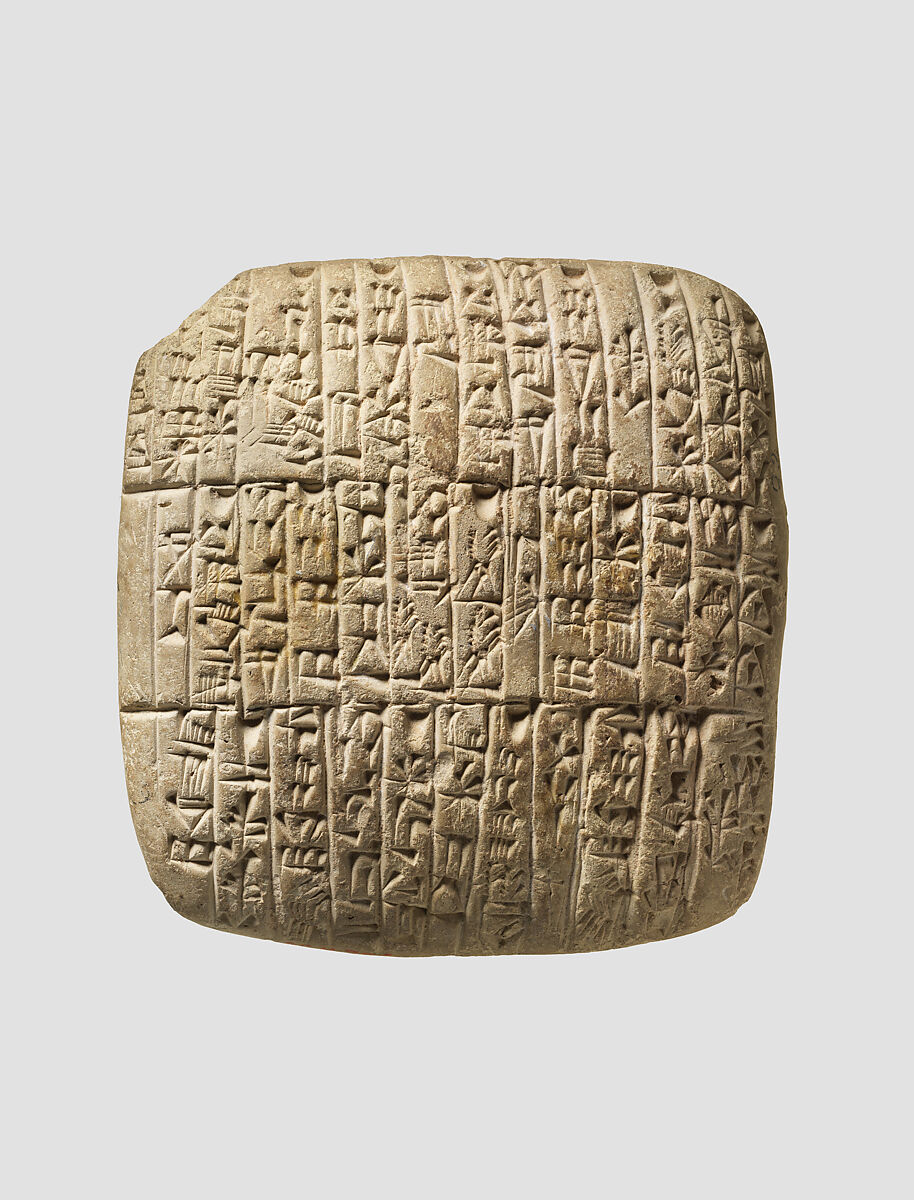
A house sale, written in clay.
This is a photograph of the real tablet in The Met’s collection. It is a transaction record, not a modern appraisal report.
The Metropolitan Museum of Art · Purchase, 1886 · 86.11.204 · Public Domain
Jump ahead to England in 1086. William I’s Domesday survey gathered information about who held property, what land was worth and how much tax it could produce.2 That was a different purpose and system from a private home appraisal today.
I would not draw a straight line from either record to the first modern appraiser. What these examples show is simpler: keeping track of property and its value has mattered for a very long time.
1930s → 1989
A growing profession develops shared standards
Modern American appraisal practice developed through professional education, mortgage lending and increasingly formal standards. The two organizations that later united as the Appraisal Institute were founded in the 1930s to advance appraisal education and ethical practice.3

Housing demand grew rapidly after World War II.4 More transactions and mortgage activity made the question of a home’s value important to many families and lenders. A recognizable suburban house might replace Rock’s cave, but describing the property and explaining its value still mattered.
A later turning point came during the savings-and-loan crisis. In 1986, nine appraisal organizations formed a committee to develop shared professional standards. The Appraisal Foundation followed in 1987 to implement the Uniform Standards of Professional Appraisal Practice, usually shortened to USPAP.5
In 1989, Congress passed FIRREA, the Financial Institutions Reform, Recovery, and Enforcement Act. Its Title XI created the Appraisal Subcommittee and helped establish the regulatory framework for appraisals in federally related transactions.6
Appraisal became more than a collection of local habits. Shared standards and formal oversight gave the profession a clearer framework for credible, independent work.
2005
The report-form change near the start of my career
I remember appraisal forms changing around the beginning of my career. The historical record points to a major revision in 2005, which fits that recollection, although I cannot identify my first changed report from memory alone.
The familiar Uniform Residential Appraisal Report carries “March 2005” in its footer: Fannie Mae Form 1004 and Freddie Mac Form 70.7
A contemporaneous announcement from appraisal-software company a la mode described the final revised forms and the November 1, 2005 requirement for their use.8 HUD also announced in September 2005 that FHA would adopt four of the revised reporting forms and eliminate duplicative paperwork.9
That is why I would describe the period as a report-form transition, rather than saying appraising itself suddenly began working a different way. The form communicates the analysis; filling in its boxes is not the same thing as developing a supported value opinion.
My early years → today
I used MLS then. The pictures got much better.
I found comparable sales through MLS when I started, much as I do now. MLS means multiple listing service. I did not begin my career hunting through stone tablets, and I do not want this history to pretend otherwise.
The difference I notice most is how much more I can see. Early in my career, a comparable often had only one listing photograph. Now there are usually many more pictures, including the inside of the house.
That makes a practical difference when I’m trying to understand what a comparable actually looked like. One exterior photograph gives me a much narrower view than a series showing the kitchen, bathrooms and other rooms. The additional photographs help me understand the property’s condition and how it compares.
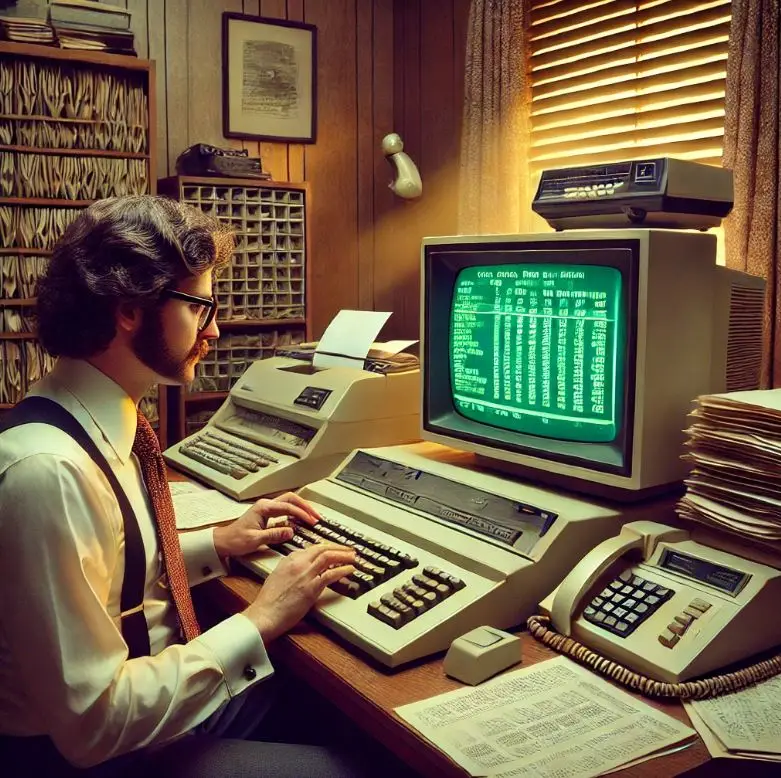
Taking my own photographs was already digital when I entered the profession. I have heard older appraisers tell stories about getting film developed, but that was their experience, not mine. In my working life, the biggest photographic change has been the amount of useful visual information available.
More pictures help me do my job. They do not choose the comparable for me or decide what adjustment is supported. I still have to interpret what I’m looking at.
For the research side of that process, I explain more in where appraisers find and verify comparable sales.
Tape + clipboard → laser + iPad
My measuring tools changed. I still carry the tape.
When I started measuring houses, I used a measuring tape and a clipboard. Today I use a laser measure and record the measurements on an iPad Mini. I still keep my measuring tape handy.
That is probably the clearest way to picture the technology change in my everyday work: I’m still at the house measuring it, but the tools I hold and the way I record the information have changed.
+ clipboard
Measure the house and record the dimensions by hand.
+ iPad Mini
Measure with the laser and record the information on the iPad.
I like the help technology gives me. Using an iPad does not mean I have stopped inspecting houses, and using a laser does not mean the tape measure has become useless. I use the tools that help me get the work done.
When people talk about appraisal becoming automated, this is the distinction I come back to. Technology can improve how I collect and organize information while I’m still responsible for understanding the house in front of me.
Measurement standards are another part of the story. My separate ANSI Z765-2021 guide explains the requirements for applicable assignments.
2009 → 2010 and beyond
Independence rules changed the business around the appraiser
One of the biggest changes I experienced was who sent me the work. I remember mortgage companies choosing the appraisers they worked with more directly. After the mortgage crisis, appraisal management companies, or AMCs, became a much more prominent part of my experience.
An AMC is a company that manages appraisal ordering and related administration for lenders. The historical sequence matters: the Home Valuation Code of Conduct arrived in 2009, followed by Fannie Mae and Freddie Mac’s Appraiser Independence Requirements in October 2010. The purpose was to protect valuation work from improper influence.1011
Those rules did not require lenders to use an AMC. Fannie Mae expressly says lenders may order directly from an appraiser or appraisal firm, provided the independence requirements are followed.11

My frustration is with the economics. In the AMC arrangements I’m describing, I estimate that roughly 40%–50% of the total charge can go to the middleman. That is my account of the arrangements I have encountered, not a verified average for every AMC or every assignment.
Some fees offered to the appraiser are around what I remember earning when I started. From my perspective, that has made this kind of work much less lucrative. I do not believe the administrative layer justifies taking that much of the fee while the appraiser carries out the inspection, research and valuation analysis.
Federal valuation-independence rules also address customary and reasonable compensation for fee appraisers in covered transactions.12 The larger pay debate belongs in my AMC reform article; it is part of this history because it changed the business surrounding the work.
Today → the next chapter
Better technology still needs an appraiser’s judgment
I do not see appraisers being replaced anytime soon. That is my professional opinion, not a prediction I can guarantee. The inspection is one reason. There are things I need to see at a property that a database may not capture adequately.
Then comes the harder part: deciding whether a difference affects value and whether the market supports an adjustment. A stream near a property or power lines behind a house may give me something to investigate. Simply noticing the feature does not tell me the correct dollar adjustment.
I still have to think about the property, the competing homes and what buyers appear willing to pay. Technology can help me find and organize the evidence. It does not remove the need to understand that evidence.
Joe’s field note: a feature is a question to investigate
When I mention a stream or power lines, I’m describing the kinds of features that can require analysis. I’m not saying that either automatically produces a positive or negative adjustment. The question is whether there is market support for an effect on this property’s value.
There are already lender pathways that do not require a traditional appraisal for every eligible transaction.11 Automated valuation models and different inspection arrangements deserve their own explanations, so I cover them in my AVM guide and hybrid appraisal overview.
Report design is changing again with the Uniform Appraisal Dataset (UAD) 3.6 and the redesigned Uniform Residential Appraisal Report. As of October 22, 2026, the November 2 mandate remains in place, with a temporary exception available to approved Sellers under the September 30 announcement.13 My UAD transition guide covers the rollout in detail.
After 20+ years of appraisal experience, my position is straightforward: I use technology to my advantage. More MLS photographs, a laser measure and an iPad all help. But I still need to inspect, compare, investigate and decide what the evidence supports.
“So the gadget helps.
Someone still has to understand the house.”
Sources & historical notes
The chronology is supported by the sources below. Personal recollections and opinions come from Joe’s October 22, 2026 interview.
- The Metropolitan Museum of Art — House-sale contract, Quradum archive; dated ca. 2350–2150 BCE. Object 86.11.204. Public-domain object photograph.
- The National Archives (UK) — Domesday survey: William I’s 1086 inquiry into property ownership, land value and tax revenue.
- Appraisal Institute — History of its two predecessor organizations in the 1930s and their 1991 unification.
- U.S. Government Accountability Office — Historical timeline of housing finance, including rapid postwar housing-demand growth.
- The Appraisal Foundation — 1986 standards committee, establishment of the Foundation in 1987, and FIRREA in 1989.
- Appraisal Subcommittee — Title XI of FIRREA and creation of the ASC in 1989.
- Fannie Mae — Uniform Residential Appraisal Report, Form 1004 / Freddie Mac Form 70, bearing the March 2005 revision date.
- a la mode, March 29, 2005 — Contemporaneous software-vendor account of the revised forms and November 1, 2005 requirement.
- HUD, September 26, 2005 — FHA adoption of four revised appraisal forms and elimination of duplicative forms.
- Fannie Mae, December 2025 — HVCC in 2009, subsequent independence rules, and clarification that lenders are not required to use AMCs.
- Fannie Mae — Property valuation FAQs: October 2010 AIR, appraiser selection and direct lender ordering.
- Consumer Financial Protection Bureau — Regulation Z §1026.42: valuation independence and customary-and-reasonable compensation provisions for covered transactions.
- Fannie Mae and Freddie Mac, September 30, 2026 — UAD 3.6 temporary policy exception; November 2, 2026 mandate remains, with exceptions for approved Sellers.
- Virginia DPOR License Lookup — License 4001012919, Joseph Thomas Ellington Jr.; active Licensed Residential RE Appraiser. Direct lookup checked October 22, 2026. Search by license number.
- Appraisal Subcommittee National Registry — Joseph Thomas Ellington Jr., Virginia license 4001012919; Licensed credential, active status and September 27, 2007 credential effective date.
The cavemen are fictional guides, and the illustrated scenes are not photographs of historical appraisal assignments. The clay tablet is an actual museum object. The new sticker illustrations are AI-generated. Joe reviewed and approved the wording and professional reasoning before publication.