
Capital Valuations · Local appraisal knowledge
Last updated
I believe your appraiser should be from the area and already know its neighborhoods. For a Virginia Beach home, I want someone with firsthand knowledge of this market. Choosing a cheaper appraiser from far away can sacrifice the local experience the assignment needs.
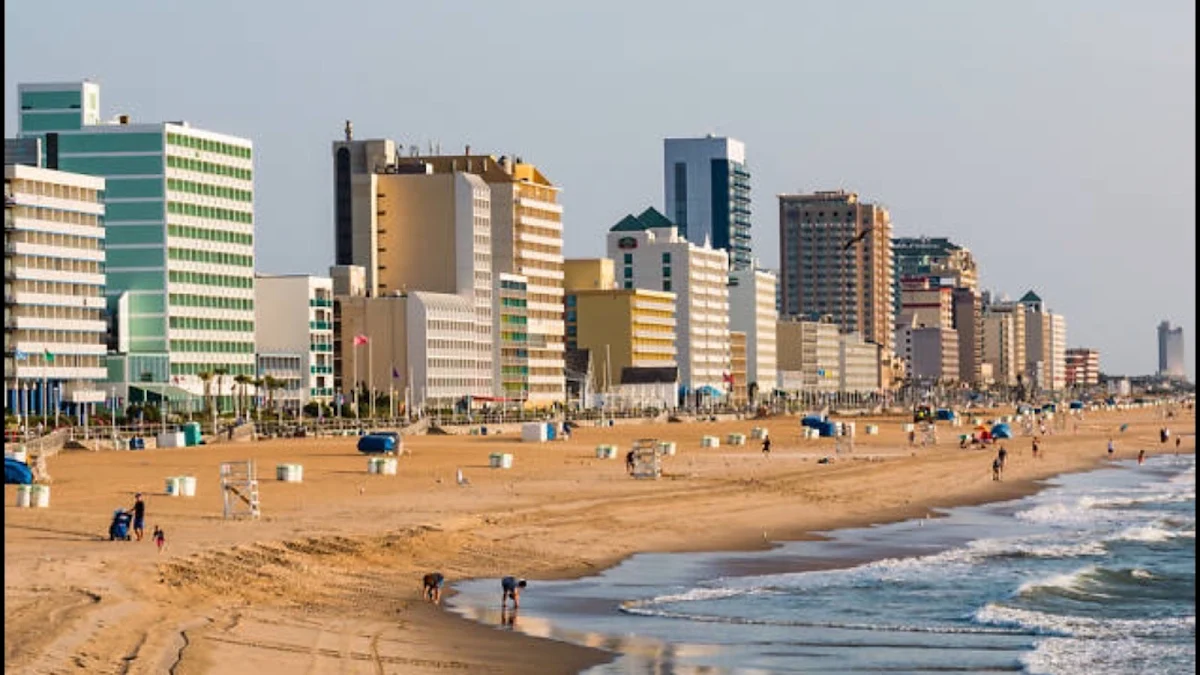
Virginia Beach has been home my whole life
When someone asks how well I know Virginia Beach, I can answer that personally. I’ve lived here my whole life, my family is from here, and I know people throughout the city. Kempsville, Chic’s Beach, Pungo, and the Oceanfront are places I know from living here, not just names I’ve looked up for an assignment.
I also have 20+ years of appraisal experience. That background matters to me, but so does recognizing the differences within the places I know. A familiar neighborhood name can cover homes and sites that are very different from one another.
That is why I feel strongly about using an appraiser from the area. The person valuing your home needs to understand the neighborhood before accepting the job. I would want that same familiarity if someone were appraising my own property.
An out-of-area appraisal that explains my concern
One example that sticks with me involved an appraiser who came to Virginia Beach from the Short Pump area near Richmond through an appraisal management company, or AMC. As I recall it, the appraiser received about $300. In my judgment, a fee of roughly $450 to $500 would have been appropriate for that assignment.
I thought the appraisal was poor because it compared neighboring areas that I knew had very different homes and values. One had newer contemporary homes. The other had homes built in the 1960s and was partway through revitalization. Being next door to each other did not make those neighborhoods interchangeable.
That is the kind of difference I expect a local appraiser to recognize. My concern was that the comparison did not properly reflect those neighborhood differences. The fee figures are my recollection and judgment about that particular assignment, not a statement of current appraisal prices.
This is why I object so strongly when an AMC puts a lower fee ahead of local experience. Saving $50 should not be a reason to pass over an appraiser who already knows the neighborhood in favor of someone from far away who does not. The question should be who is qualified for this home and this market.
Kings Grant: the same neighborhood can contain meaningful differences
Kings Grant is one of the examples I think of immediately. People sometimes treat the front and the back of the neighborhood as though they are interchangeable. In my experience, you can travel a short distance within Kings Grant and encounter a very different property setting and value range.
That is why I would not look at a sale and say, “It’s in Kings Grant, so that must be what your house is worth.” Where the land sits matters. Sharing a neighborhood name does not mean two properties offer the same thing.
The next step is to investigate the difference: the site, the house, its condition, and the sales evidence relevant to that property. A higher sale price elsewhere in the neighborhood does not, on its own, establish a location adjustment. My guide to choosing comparable sales explains the selection process in more detail.
Bring firsthand experience of the market before accepting the assignment.
Recognize why nearby neighborhoods, and parts of one neighborhood, can differ.
Connect that local understanding to the property and relevant market evidence.
Conceptual guide, not a map or a calculation of property values.
The Oceanfront is more than one broad location label
I live at the Oceanfront, and it is another place where I see the problem with broad labels. The area includes different pockets of homes. Calling a property “at the Oceanfront” does not tell me enough about its particular setting or how it compares with another home nearby.
Living here gives me a connection to those places. When I am appraising, though, I need to understand the actual home and the part of the area it belongs to. I would not treat the entire Oceanfront as one uniform neighborhood.
Appraisal quality should come before the lowest fee
For mortgage assignments subject to Fannie Mae’s requirements, the selected appraiser must already have the necessary knowledge of the location and property type, along with access to appropriate local data. Its selection requirements also put work quality ahead of fee and turnaround time. Using an AMC does not remove the lender’s responsibility for the work. [2]
That is the priority I want to see in practice. Local experience should matter when the assignment is made. A homeowner should not lose the benefit of that experience because someone is willing to take less money for the job.
Knowing my limits is part of serving the client
I apply that same standard to myself: if I am not familiar with the area, I will not accept the assignment. I want the client to receive credible results, and I have to be honest about whether I am the right person to provide them.
There have also been times when I accepted an assignment, went out to the property, and realized I could not provide the satisfactory appraisal the client deserved. In those situations, I have explained the issue and returned the client’s money. I would rather do that than press ahead with work I am not comfortable completing.
Sometimes a property turns out to be different from what I expected before seeing it. I take that seriously. Accepting an order is not a reason to ignore a concern that comes up afterward. Being honest with the homeowner matters more to me than keeping an assignment.
I also check whether the appraisal will serve your purpose
One of the first things I ask when someone calls is why they need an appraisal. I regularly hear from homeowners who are refinancing through a mortgage company and think they need to hire an appraiser themselves. I tell them to speak with their lender about its ordering process first. I do not want to sell someone an appraisal they cannot use.
For loans subject to Fannie Mae’s requirements, the lender or its authorized agent selects the appraiser; the lender cannot use an appraisal ordered by the borrower. Check your particular lender’s requirements before paying for a separate private report. [2]
The client’s need comes first. That means knowing the area, recognizing the limits of my experience, and being honest about whether an appraisal I provide will serve the purpose.
Tell me about your property and what you need
For a private appraisal inquiry, send me the property address and the reason you need a value opinion. I can discuss whether the assignment is a fit. If you are comparing professionals, my separate guide to choosing a local appraiser covers credentials and the questions to ask before hiring.
Editorial note: Developed from my firsthand account, with AI assistance for research, organization, and drafting.
Sources and further reading
The neighborhood observations, out-of-area assignment example, fee recollections, and restaurant recommendation come from my own account. My recommendation to choose an appraiser from the area is my professional opinion. The sources below support the standards, credential, and restaurant details; they do not independently verify my anecdote or establish a universal mileage limit.
- The Appraisal Foundation, 2024 USPAP, Competency Rule, pages 13–14. Public copy hosted by Bastrop Central Appraisal District; competency, acquiring knowledge, and withdrawing when competent completion is not possible.
- Fannie Mae Selling Guide, Appraiser Selection Criteria. Existing geographic and property-type knowledge, data access, quality taking priority over fee or turnaround time, and lender responsibility for applicable mortgage assignments.
- Appraisal Subcommittee, Joseph Thomas Ellington Jr. Virginia credential 4001012919; registry lists the credential as Licensed and Active, expiring September 30, 2027.
- Icehouse Restaurant’s official website and menu. Norfolk Avenue location and French dip listing. The recommendation is my personal opinion.