
By Joseph T. Ellington Jr. – Licensed Residential Appraiser, Capital Valuations.
Last updated
Extraordinary assumptions in a real estate appraisal
The practical question is what is uncertain, why the appraiser has a reasonable basis for the assumption, and how the value conclusion depends on it. An assumption should help the reader understand an unresolved fact. It should not hide an observation, excuse a missing investigation, or make an unfavorable property condition disappear.
Start with the effective date and the known facts
A current inspection, a past valuation date and a proposed future condition answer different questions. Before ordering, explain which date matters and what the property was like on that date. Provide the records available: photographs, plans, permits, invoices, repair estimates or other reliable information. The appraiser decides whether the evidence supports the required analysis and whether more investigation is necessary.
For example, an estate assignment may require a value as of an earlier date. The house’s condition at that time might need to be reconstructed from dated records and interviews. The report should distinguish observed present-day conditions from evidence about the earlier date and explain any material uncertainty that remains.
Uncertain versus known to be different
Consider two hypothetical renovation situations. In the first, reliable records suggest that a concealed feature has a particular condition, but that condition cannot be directly verified within the agreed scope. Whether an extraordinary assumption is appropriate depends on the assignment, the supporting basis and professional requirements. The appraiser may instead require additional evidence or decline to rely on the assumption.
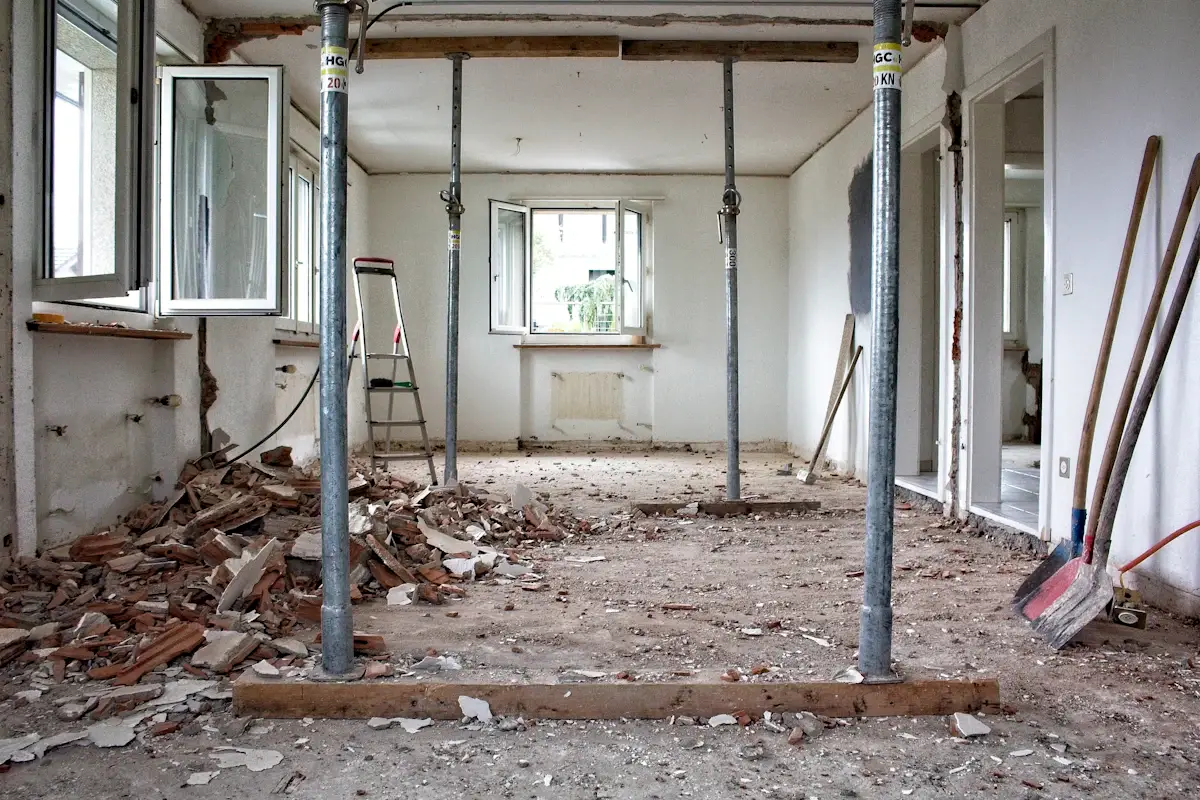
In the second, a kitchen is visibly unfinished on the effective date, but the requested analysis treats a specified renovation as complete on that same date. Completion is contrary to the known condition. That calls for considering a hypothetical condition, rather than describing known unfinished work as an uncertain fact. A prospective valuation at a future date raises a different set of forecasting and scope questions.
These examples explain the distinction; they are not instructions to apply either device automatically. The report needs to identify the assumption or condition and explain its effect on how the results should be understood.
Questions to ask when reading the report
- Which specific fact is uncertain or treated differently from what is known?
- What information supports the appraiser’s treatment of that fact?
- What intended use and effective date does the report address?
- Would the conclusion remain useful if the assumed fact proves false?
- Does the intended user require inspection, verification or completion evidence before relying on the report?
If later evidence contradicts an important assumption, contact the appraiser. Do not silently remove the qualification from the report or reuse the conclusion as though it addressed a different property condition. The appraiser can explain whether an update, additional analysis or a new assignment is needed.
What to send before the assignment begins
Share the property address, intended use, requested effective date, known access restrictions and all material condition information. For renovation work, identify what is finished, what is proposed and what documentation exists. For historical assignments, dated photographs and records can be more useful than an undated description of how the property used to look.
An extraordinary assumption concerns an assignment-specific uncertain fact that the appraiser assumes is true for the analysis. If the assumed fact turns out false, it could affect the conclusions. It is not a license to invent a favorable property condition. The report should make the assumption and its possible effect clear. See the Appraisal Institute guide notes and applicable USPAP for the exact requirements.
A practical distinction
| Concept | What it means | Illustrative situation |
|---|---|---|
| Extraordinary assumption | A relevant fact is uncertain and assumed true with a reasonable basis | Limited access prevents confirming a stated feature, subject to a credible scope |
| Hypothetical condition | Something known to be contrary to fact is assumed for analysis | Value as if a planned renovation were completed when it is not |
These examples illustrate definitions, not a claim that either condition is appropriate for every assignment. An appraiser must decide whether the scope, premise, and disclosures allow credible results. A lack of time does not automatically justify assuming away a material defect.
Check the evidence and the assignment scope before relying on a reported figure.
Questions a client can ask
- What specific fact is unknown?
- Why is there a reasonable basis for the assumption?
- What evidence would resolve the uncertainty?
- Could a different fact materially change value?
- Is the intended use compatible with the resulting report limitation?
For a retrospective estate assignment, past condition may need evidence from dated photographs, permits or prior listings. A client should not expect an extraordinary assumption to replace available research. Read our date-specific estate guide. For a planned repair or as-repaired scenario, ask whether a hypothetical condition is needed; see our as-is sale discussion. For planned construction, see how a completed-condition premise should be defined before the assignment.
To discuss an appraisal with an unusual property fact in Hampton Roads, contact Capital Valuations with the property, intended use and available records.
