
Last updated
By Joseph T. Ellington Jr., Virginia Licensed Residential Appraiser, Capital Valuations
The home appraisal process starts with the property address and why you need a value. I inspect and measure the home, research comparable sales, analyze the evidence, and prepare a report. This guide explains those steps, including the work that continues after I leave your house.
I’m Joe Ellington, owner of Capital Valuations in Virginia Beach. In my 20+ years of appraisal experience, one of the most common questions has been whether I can give someone the value as soon as I finish measuring. The visit gives me the property information I need. The research that turns those observations into a supported opinion of value happens afterward.
Here is how I approach a typical residential appraisal with an interior and exterior visit in Hampton Roads.
1 Start with the address and the purpose
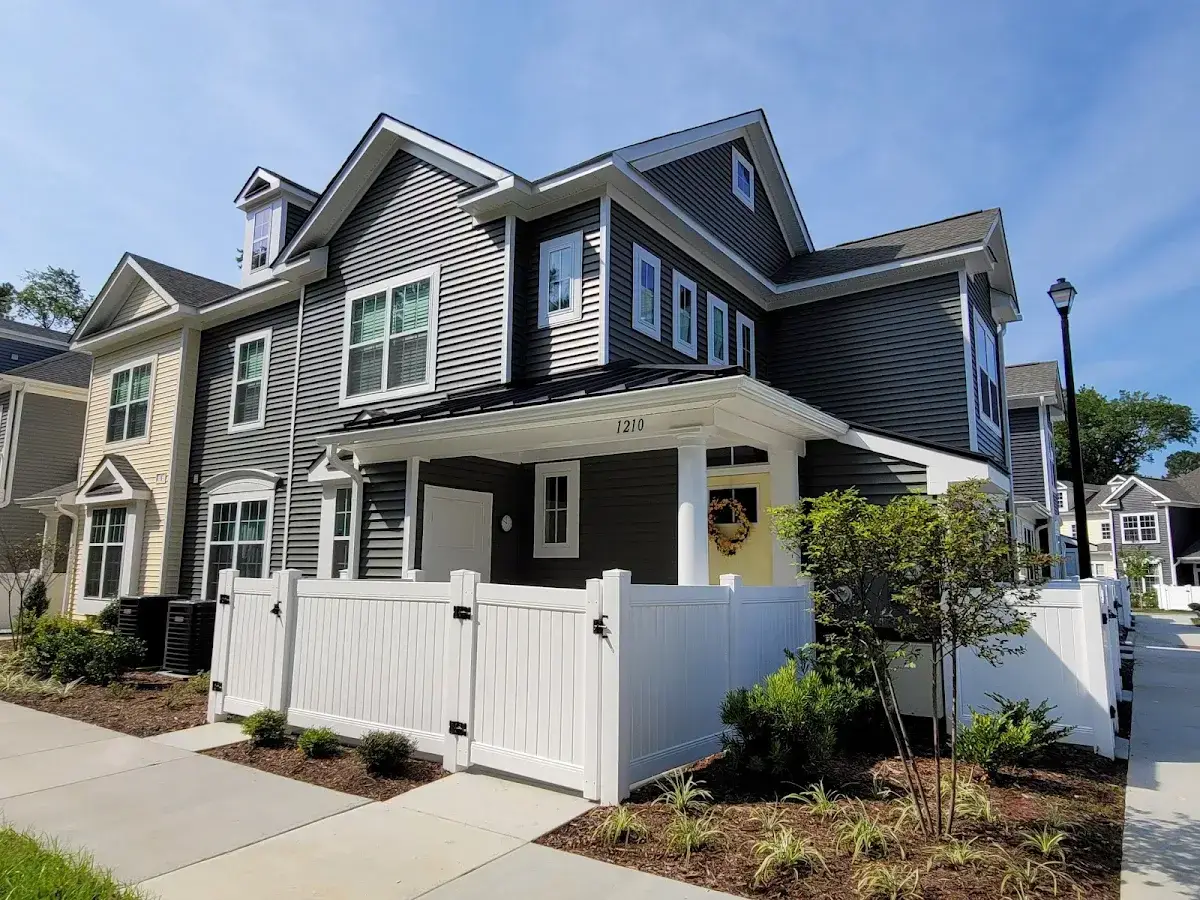
When someone calls, my first question is usually, “What’s the property address?” That lets me take an initial look at the house and begin working out a quote.
Then I ask why they need the appraisal. Someone preparing to list a house needs a different assignment from someone handling an estate who needs a value as of a past date. The purpose helps me establish the scope of work: what the appraisal needs to answer, what research is necessary, and how the results should be reported.
You do not have to know the correct appraisal terminology before calling. Tell me what you are trying to accomplish. I can help you work through whether you need a pre-listing appraisal, a date-of-death appraisal, or another residential valuation service.
For a private assignment, we identify the client, who will use the report, and the date the value needs to apply to. If the appraisal is for a mortgage, start with your lender and follow its ordering process.
2 Agree on the scope and expectations
Before scheduling, we discuss the property, appraisal purpose, fee, access, and expected delivery date. If you need a value as of an earlier date, tell me at the beginning. The date I visit the house and the date the value applies to may be different.
My typical property visit takes 30 minutes to an hour. A straightforward ranch with a simple footprint often takes about half an hour. Larger properties and more complicated layouts take longer.
My usual report turnaround is one to two business days after the inspection. That is the normal expectation, with the specific deadline agreed for your assignment. Property complexity, missing information, access problems, or limited comparable sales can affect the schedule.
The fee covers the inspection, research, analysis, and report. I review the address and purpose before quoting because the amount of work can vary considerably between assignments.
3 Inspect and measure the home
Before arriving, I look at the address and available MLS information to get an initial understanding of the property. I still need to see the house myself to understand its current layout, size, and overall condition.
I usually start outside
I photograph the front of the house and the street, and note visible features such as the foundation type and exterior materials. After introducing myself, I explain that I will usually start outside and ask for access through any gate and into the garage.
I work around the property, taking side and rear photographs and documenting features such as porches, patios, sheds, and pools where present. I also note and photograph visible equipment and components relevant to the assignment, such as the exterior HVAC unit.
If there is a garage, I generally measure it early in the visit. I document accessible features there, which may include the water heater, electrical panel, or attic access. Then I continue measuring the house and its other relevant areas.
Inside I record the layout and condition
I walk through the rooms, take photographs, and note the materials, features, and condition. Where an upper floor cannot be adequately measured from the lower level, I take the additional measurements needed upstairs.
I take notes throughout. Those notes help me connect what I observed at the property with the information I use later in the report.
The appraisal visit is not a technical inspection of the electrical, HVAC, plumbing, or other building systems. Photographing a component does not establish that it operates correctly. A specialist’s inspection may answer questions that an appraisal does not.
I save the detailed homeowner conversation for the end
I like to see and document the house before sitting down to discuss it. By then, I know what I am working with and can ask more useful questions.
It helps if you let me concentrate while I am measuring and taking notes, then we can go through your updates and questions together. Please tell me about an immediate safety or access issue right away.
At the end, I want to hear about improvements, when they were completed, known problems, and anything I may not have been able to see. Work behind a wall can be relevant even when there is nothing obvious to photograph.
Why I take my own measurements
I use my own measurements and the applicable reporting method rather than simply copying a square-footage figure from a listing or public record.
In my experience, those figures can differ, particularly with upper floors or areas that have been changed. The reason needs to be examined; a difference alone does not establish which published figure is wrong.
Measuring and documenting the property gives me a basis for the area reported in my appraisal. If your main question is about square footage, my home measuring services explain that separate service.
4 Research comparable sales after seeing the house
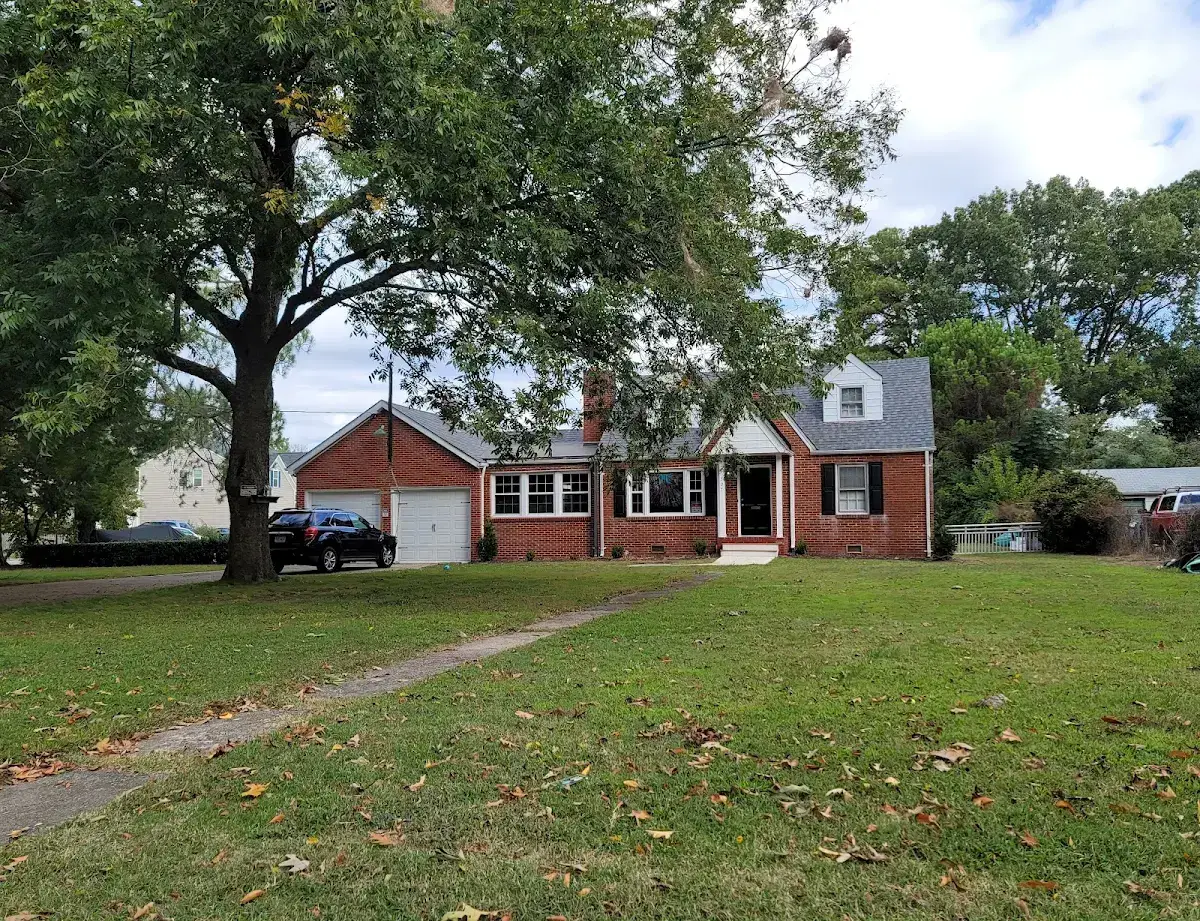
For this type of assignment, I wait until I have inspected the home before selecting my comparable sales.
Earlier in my career, I sometimes did much more comparable research before the appointment. Then I would arrive and discover that the house had additional space or had been renovated since the information I had reviewed. The properties I had pulled were no longer the best fit.
That experience changed my workflow. I want to understand the house’s actual size and condition before deciding which sales are most useful.
Back at the office, I research sales that competed with the property. If the best matches are not available nearby, I may need to expand the search area or look farther back in time. I evaluate differences in location and market conditions and make adjustments when the evidence supports them. Distance or age alone does not create an automatic adjustment.
The goal is to find relevant market evidence and explain why I used it. For applicable mortgage assignments, Fannie Mae’s guidance also recognizes that a sale from a competing area or an earlier period can be appropriate.
5 Analyze the differences and develop the value
Comparable homes rarely match in every respect. I look at meaningful differences, including size, location, layout, quality, and overall condition, and analyze how buyers respond to them.
This is where renovation cost and market value often get confused. The amount you paid for an improvement is useful information. Its contribution to value depends on what buyers recognize in the market.
A simple illustration of cost versus value
Suppose two otherwise similar homes sold under comparable conditions, one for $100,000 without a pool and one for $110,000 with a pool. If the evidence supported attributing that difference to the pool, it would suggest a $10,000 contribution in that comparison—even if the installation cost was $20,000.
Those are hypothetical numbers to explain the idea, not a local sale example or a standard pool adjustment. In an actual appraisal, I would investigate other differences and consider additional evidence before reaching a conclusion.
The same reasoning applies to other improvements. A renovation invoice does not automatically translate into an equal increase in appraised value.
After analyzing the sales, I weigh the evidence to reach the final opinion. The conclusion needs to explain which comparable sales provide the strongest support and why; it is not simply an average of their prices.
6 Complete the analysis and write the report
The work after the visit is the part clients do not get to watch. I return to the office, research comparable properties, analyze the differences, and put the findings together in the report.
On a difficult assignment, that work can take me eight to ten hours. A half-hour visit does not mean the entire appraisal took half an hour.
The report connects the property information with the market evidence. It explains the assignment, the relevant date, the analysis, and the value conclusion, along with any assumptions or conditions the reader needs to understand.
That is why I do not give an off-the-cuff value at the door. I still have work to do before I can support the answer.
7 Read the explanation and then review the comparable grid
When you receive my report, I recommend reading the narrative addenda first. That is where you can find the explanation behind the analysis. Then look at the comparable-sales grid to see how the properties and adjustments fit together.
Check the property details and relevant date as well. If you spot a possible factual error, call or send me a message with the specific item and any supporting information. I can review it and address any correction that is needed. Whether it changes the value depends on its significance.
If the value is different from what you expected, I can explain the reasoning. One useful way to discuss it is to consider the alternatives available to buyers. Appraisers call this the principle of substitution.
For a current-value assignment, relevant active or pending listings can help illustrate those alternatives. If a similar or superior house is offered for less than an owner expects for theirs, that deserves examination. Asking prices and pending transactions provide context; they are not the same evidence as verified closed sales.
For lender-ordered work, follow the lender’s process for report questions or a reconsideration request. For a private report, use the communication arrangements agreed for the assignment. My guide to reading an appraisal report goes into more detail.
What to prepare before I arrive
A written improvement history is one of the most useful things you can give me. Include what was done and roughly when it was completed. Dates help me understand the house much better than a general statement that it has been “updated.”
Have these items ready when available:
- A list of renovations, replacements, and additions, with completion dates.
- Relevant invoices, permits, plans, surveys, or other property records.
- Information about known damage, repairs, or improvements I may not be able to see.
- Access to the rooms, garage, and exterior areas needed for the visit, with gates unlocked and pets secured.
- Dated photographs or records showing the earlier condition when the appraisal concerns a past date.
You do not need to create a presentation or have every document on this list. Share the useful information you have, and tell me when a date or detail is approximate.
Questions homeowners often ask
Does my house need to be spotless
Homeowners often apologize for clutter or ordinary housekeeping. Everyday untidiness is usually much less important to my analysis than they think.
Focus on clear, safe access so I can see and measure the property. Clutter that prevents access or hides a condition issue is a different situation from a lived-in home that has not been staged for photographs.
Do you look in every room
For my typical interior and exterior appraisal, plan to make every room accessible so I can document the layout and condition. Let me know beforehand about locked rooms, tenant arrangements, or restricted areas.
Some appraisal assignments use a different inspection scope. Confirm what is included when the work is ordered.
Can I give you sales I think are comparable
Yes. You can provide sales and explain why you think they are relevant. I will evaluate them along with the other evidence. An owner’s records and knowledge of the property can be helpful, while the selection and analysis remain my responsibility.
What should I ask before hiring a private appraiser
Ask how long the appraiser has been doing this work, whether they know your local market, and whether they handle the type of assignment you need.
My personal preference would be someone with at least ten years of appraisal experience. That is a preference, not a licensing requirement or a substitute for relevant knowledge and appropriate qualifications. Ask who will inspect the property and who will explain the report if you have questions.
What if the appraisal is lower than the purchase price
Read the report and discuss the financing implications with your lender. The appraisal develops an opinion of value; it does not decide the loan or the terms the buyer and seller must accept.
If you identify a factual problem or relevant evidence that may have been overlooked, ask about the lender’s review process. Discuss any contractual options with your agent or legal adviser.
Talk with me about your appraisal
My goal is for you to understand what happened, why the work was needed, and how the conclusion was reached. You should be able to ask questions and get an explanation in regular language.
If you need a private residential appraisal in Hampton Roads, send me the property address, the purpose, the required valuation date, and your deadline. I can help you identify the appropriate service and discuss the fee and timing.
Contact Capital Valuations or call 757-831-6234. If you are preparing to sell, you can also read about my pre-listing appraisal services.
Sources and further reading
My descriptions of the visit, research sequence, typical timing, and client conversations reflect my own appraisal practice. The following references provide additional information; Fannie Mae’s requirements apply to the relevant lending assignments.
- Fannie Mae — Comparable Sales: selection of competitive properties, including appropriate older sales or sales from competing areas.
- Fannie Mae — Adjustments to Comparable Sales: market support for adjustments and the analysis of value indications.
- Appraisal Institute — Interacting With Appraisers: providing useful information, understanding the report, and asking questions.